 Max Gallagher · Mortgage Adviser
Mortgage adviser in Harwood
Harwood is almost entirely residential, from the homes around Longsight Park out to the quieter lanes towards Bradshaw and Affetside, and it sits right on the Bury border, as do I: my office is on Walshaw's High Street, just the other side of Ainsworth. Whether you are buying your first Harwood home, moving for space on the Bradshaw side, or remortgaging a house you have owned for years, I guide you from application to completion.
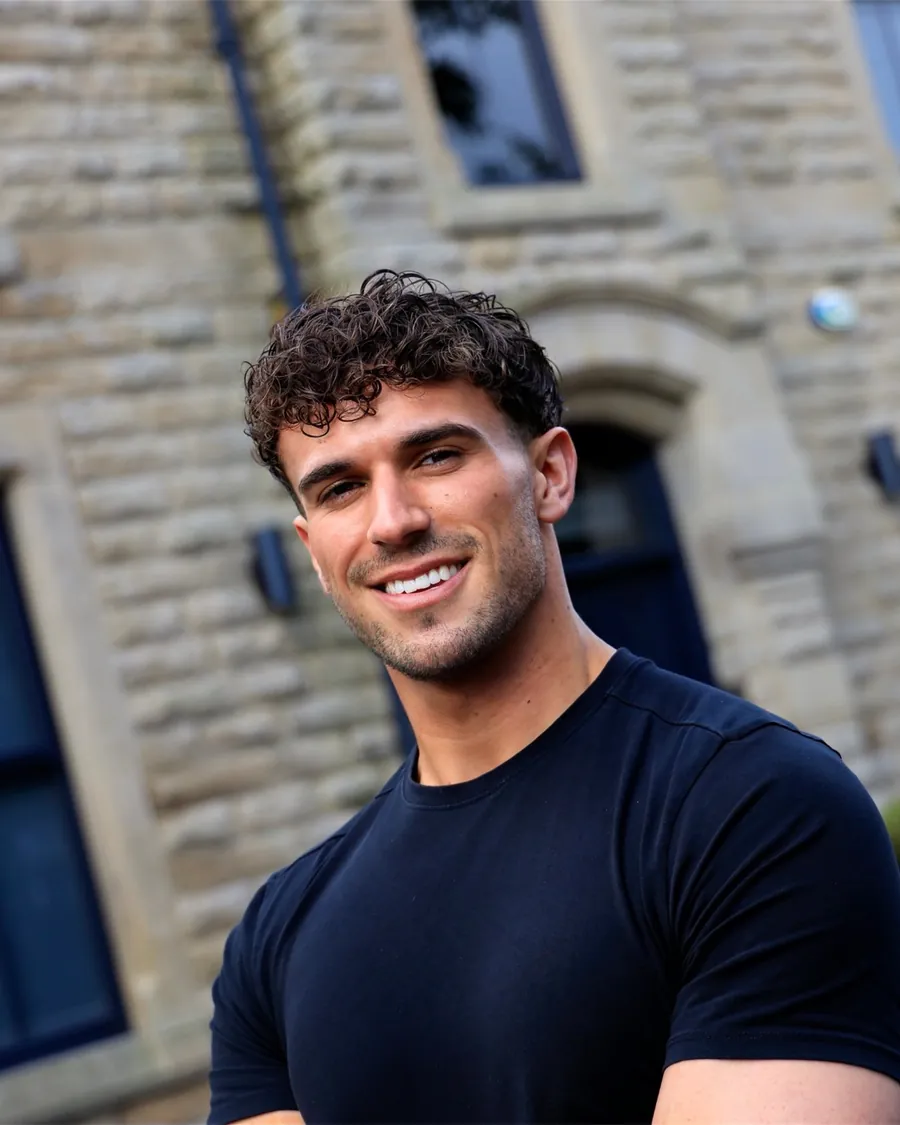
If you have been searching for a mortgage broker in Harwood, that is the job I do. I am Max Gallagher, the Mortgage Expert with Financial Options Group. I compare lenders, recommend the one deal that fits, and run the application through to completion, chasing the lender, the solicitor and the estate agent so you do not have to. The first conversation is free, at my office, at your home in Harwood, or by Teams or phone.
5.0 on Google·160+ reviews·CeMAP qualified·Free first meeting
Your home may be repossessed if you do not keep up repayments on your mortgage.
First-time buyers in Harwood
First-time buyers in Harwood usually look at the semis near the shops and Longsight Park, and having an agreement in principle ready lets you make an offer that estate agents take seriously.
Most first-time buyers start with three questions: how much deposit do I need, how much can I borrow, and will a lender say yes to me? Deposits of five to ten per cent are common, gifted deposits from family are usually fine when documented properly, and a Lifetime ISA bonus can count towards one. Affordability is set by each lender's own rules on income, outgoings and existing credit, which is why two lenders can give very different answers to the same buyer. I get you an agreement in principle before you view, so an offer carries weight, and I explain the whole process in plain English from offer to keys.
Moving home or remortgaging in Harwood
Harwood is somewhere people settle, so most of my work here is remortgages as fixed rates end and moves for more space towards Bradshaw, often with borrowing for an extension in the mix.
If your fixed rate is ending, the work starts about six months before, when most lenders will let you reserve a new deal. Your current lender's product transfer is quick, but it is one offer from one lender, and a remortgage elsewhere can undercut it, especially if the value of your home has risen and you now sit in a lower loan-to-value band. If you are moving, we look at whether your existing deal can be ported to the new property, how any early repayment charge affects the timing, and how much extra borrowing the move or an extension needs.
Buy-to-let mortgages in Harwood
Landlords in Harwood come to me for two reasons: a first buy-to-let, or a let-to-buy where they keep the current home and rent it out when they move.
Buy-to-let lending works differently from a residential mortgage. Lenders typically want a larger deposit, usually around a quarter of the purchase price, and they test whether the expected rent covers the mortgage payment with a margin to spare. First-time landlords, limited company purchases and let-to-buy, where you keep your current home and rent it out when you move, each have their own lender rules, and I will explain the tax and structure questions you should put to your accountant before you commit. Some buy-to-let mortgages are not regulated by the Financial Conduct Authority.
Protecting your mortgage
A mortgage is usually the biggest commitment a household ever makes, so I look at what happens to it if you could not work, fell seriously ill or died. Life cover sized to the loan, critical illness cover and income protection are the three building blocks, and the right mix depends on your employer's sick pay, your savings and who relies on your income. I have won the Protection Hero award twice, in 2024 and 2025, for exactly this kind of work, and I would rather you had cover that fits than the policy the lender happened to offer.
How mortgage advice works with me
Free first chat
At my office in Walshaw, at your home in Harwood, or by Teams or phone.
Agreement in principle
Know your budget, so estate agents take your offer seriously.
Your recommendation
I compare lenders and recommend one deal, explained in writing.
Application to offer
I handle the paperwork and chase everyone through to your offer.
Completion and beyond
A reminder before your rate ends, so you never drift onto the standard variable rate.
Your initial consultation is free, with no cost and no obligation to proceed.
Mortgage questions from Harwood
Are you a mortgage broker or a mortgage adviser?
Both words describe the same job in practice. I am the Mortgage Expert with Financial Options Group: I compare lenders, recommend one deal and manage the application through to completion. If you searched for a mortgage broker in Harwood, this is the service you were looking for.
Do I need to come to Bury to see you?
No. Plenty of Harwood clients never visit the office. I can meet you at home, or we can do everything by Teams and phone with documents shared securely. If you would like to come to Walshaw, you are welcome at my office.
How much deposit do I need to buy in Harwood?
It depends on the lender and your circumstances more than on the town. Some lenders will lend with a five per cent deposit, most give better rates at ten per cent and above, and buy-to-let usually needs around a quarter. I will tell you what your deposit and income can reach before you start viewing.
My fixed rate ends soon. When should I talk to you?
About six months before it ends. That is when most lenders let you lock in a new deal, and it leaves time to compare a remortgage against your current lender's offer without rushing. If it has already ended and you are on a standard variable rate, get in touch today.
Mortgage advice nearby
I arrange mortgages across North Manchester, and each area has its own page.